Market overview and structural significance of the Stone Crushing Equipment Market
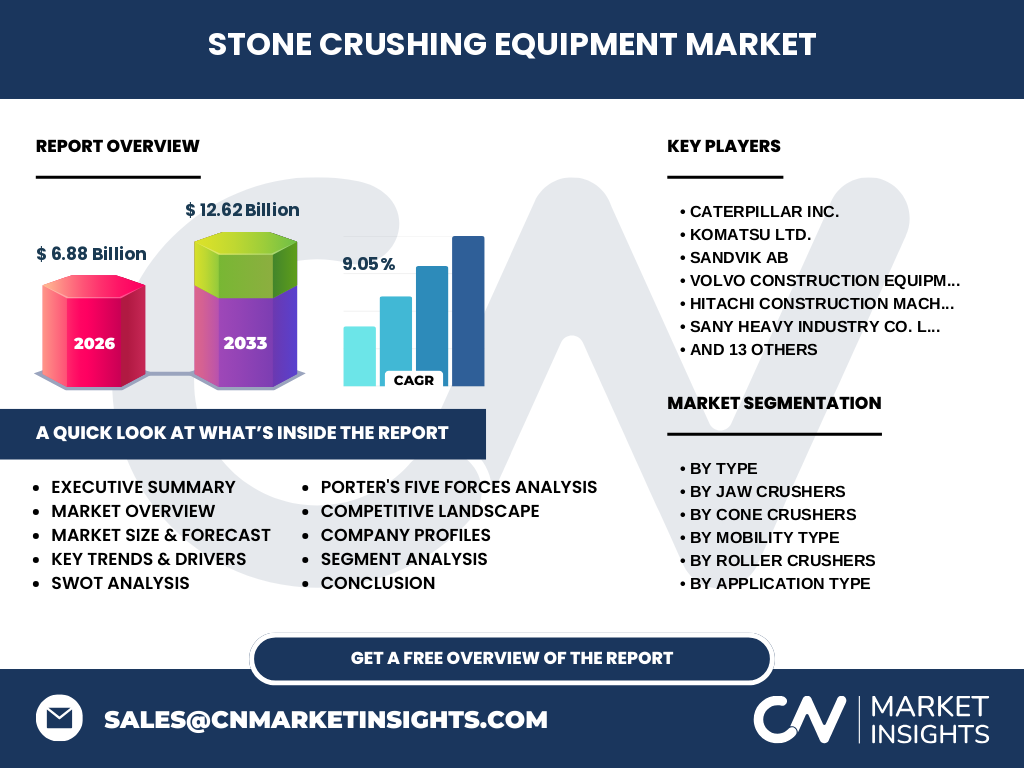
Our analysis indicates that the Stone Crushing Equipment Market valued at 6.88 Billion in 2026, forms the backbone of global aggregate production. This sector processes raw materials like granite and limestone into graded construction aggregates. Regulatory compliance with bodies such as OSHA and MSHA drives equipment evolution, ensuring particulate emission control during jaw and cone crushing operations.
What are the primary growth drivers and operational restraints shaping the industry?
The market is propelled by aggressive urbanization and highway expansion, which heavily utilize jaw crushers and impact crushers. However, high capital expenditure and stringent environmental regulations regarding noise and dust act as notable restraints. Equipment manufacturers must navigate logistical hurdles in transporting heavy primary crushers to remote quarrying sites.
Emerging trends and technological shifts in processing machinery
The shift toward automated processing plants is transforming the sector, with hydraulic cone crushers featuring IoT-enabled telemetry gaining rapid adoption. Companies like Sandvik AB and Metso Outotec lead this trend by integrating predictive maintenance into their mobile crushing units, minimizing costly downtime for road construction companies and aggregate producers.
COVID-19 impact analysis and post-pandemic recovery trajectory
Pandemic-induced supply chain disruptions severely constricted raw material flows for foundries casting manganese steel wear parts. Despite initial setbacks, the market rebounded swiftly as government stimulus packages prioritized infrastructure spending. Demand surged for automated mobile crushing equipment capable of operating with leaner on-site workforces.
Competitive Benchmarking and Market Concentration
The Stone Crushing Equipment Market exhibits a moderately consolidated structure. Industry titans like Caterpillar Inc., Komatsu Ltd., and Terex Corporation dominate through extensive global dealer networks. Meanwhile, specialized innovators such as Keestrack and RUBBLE MASTER HMH GmbH carve out high-margin niches in compact, fuel-efficient mobile recycling plants.
Executive Summary: High-Level Synthesis of Industry Dynamics
Driven by robust infrastructure investments, the Stone Crushing Equipment Market is projected to reach 12.62 Billion by 2033, expanding at a notable CAGR of 9.05%. Strategic consolidation, electrification of heavy machinery, and stringent recycling mandates represent the primary levers shaping long-term enterprise profitability across this industrial landscape.
Long-Term Market Forecast and Expansion Trajectory (2027-2033)
Our research forecasts a stellar expansion path, with the market surging from 6.88 Billion in 2026 to 12.62 Billion by 2033 at a CAGR of 9.05%. This growth is underpinned by escalating mining extraction activities and massive urban renewal projects requiring high-capacity double toggle jaw crushers and tertiary short head cone crushers.
Comprehensive Segmentation Analysis across Equipment and Applications
Market segmentation is defined by type, mobility, and end-use. Equipment types span Jaw Crushers, Roller Crushers, and Cone Crushers, further categorized into specialized variants like Single Toggle and Symons Cone models. Mobility spans stationary units versus flexible mobile plants, serving mining, quarrying, and recycling applications for road construction enterprises.
Geographic Distribution and Regional Performance Overview
Regional performance varies significantly, with the Asia-Pacific zone capturing dominant market share due to relentless urban expansion in China and India. Conversely, North America and Europe exhibit high replacement demand, prioritizing advanced, low-emission hydraulic cone crushers that comply with strict local environmental standards.
In-Depth Regional Review of High-Growth Zones
Emerging economies in Southeast Asia and Latin America represent the fastest-growing regional pockets. Increased foreign direct investment in transport corridors has spurred local quarries to procure robust impact crushers and single roll crushers, mitigating reliance on imported aggregates and optimizing regional supply chain resilience.
Strategic Positioning of Leading Industry Players
Major enterprises deploy distinct competitive strategies: Sany Heavy Industry Co. Ltd. and XCMG leverage cost-effective manufacturing for developing markets, whereas Volvo Construction Equipment AB and Liebherr-International AG focus on premium, eco-friendly drive systems. Companies like McLanahan Corporation and Astec Industries Inc. maintain strongholds in custom-engineered quad roll crushers and washing systems.
Porter's Five Forces Analysis of Competitive Intensity
The threat of new entrants remains low due to high R&D costs and stringent safety certifications. Supplier power is moderate, moderated by the specialized metallurgy required for crusher mantles. Rivalry is intense among established OEMs, driving continuous innovation in smart diagnostics, fuel efficiency, and dust-suppression technologies.
SWOT Analysis of the Stone Crushing Equipment Sector
Strengths include robust mechanical durability and advanced automation. Weaknesses involve high upfront capital and transport logistics. Opportunities lie in circular economy aggregate recycling and smart telematics. Threats stem from volatile raw material costs, specifically high-grade steel and electronic component shortages.
Value Chain Analysis from Raw Materials to End-Users
The value chain initiates with raw alloy procurement—such as high-manganese steel—proceeding through precision casting, CNC machining, and automated assembly by OEMs like HAZEMAG & EPR GmbH. Distribution occurs through certified dealer networks, ultimately supplying construction companies and recycling plants with durable reduction machinery.
Strategic Investment Insights and High-Potential Areas
Investors should direct capital toward modular, electric-powered mobile crushing equipment. As urban centers enact zero-emission zones, recycling plants processing construction and demolition waste represent high-yield opportunities, favoring agile OEMs capable of delivering rapid deployment and low carbon footprints.
Conclusion and Strategic Takeaways for Industry Stakeholders
Sustained by a 9.05% CAGR leading to 12.62 Billion by 2033, the market rewards proactive technological integration. Stakeholders must pivot toward automated, hybrid-electric crushing spreads to capture market share amid tightening environmental mandates and evolving infrastructure demands.
Research Methodology and Baseline Estimation Triangulation
Our baseline estimates are rigorously triangulated by combining proprietary customs trade registries, primary interviews with C-level executives at firms like Parker Plant Limited and Superior Industries Inc., and secondary macroeconomic indicators tracking global cement and aggregate consumption indices.
Scope of the Report and Analytical Parameters
This report encompasses global shipment volumes and revenue valuations across jaw, cone, and roller crusher segments from 2027 to 2033. Limitations include localized tariff fluctuations and unrecorded informal-sector quarrying activities in developing economies, which are modeled via econometric normalization.
Recent Industry Developments and Strategic Corporate Moves
Recent market activity highlights heavy investment in autonomous operations. Industry leaders have launched hybrid-electric mobile units designed to curtail diesel consumption. Strategic partnerships between equipment manufacturers and software developers are accelerating the deployment of AI-driven particle size analysis in modern crushing spreads.